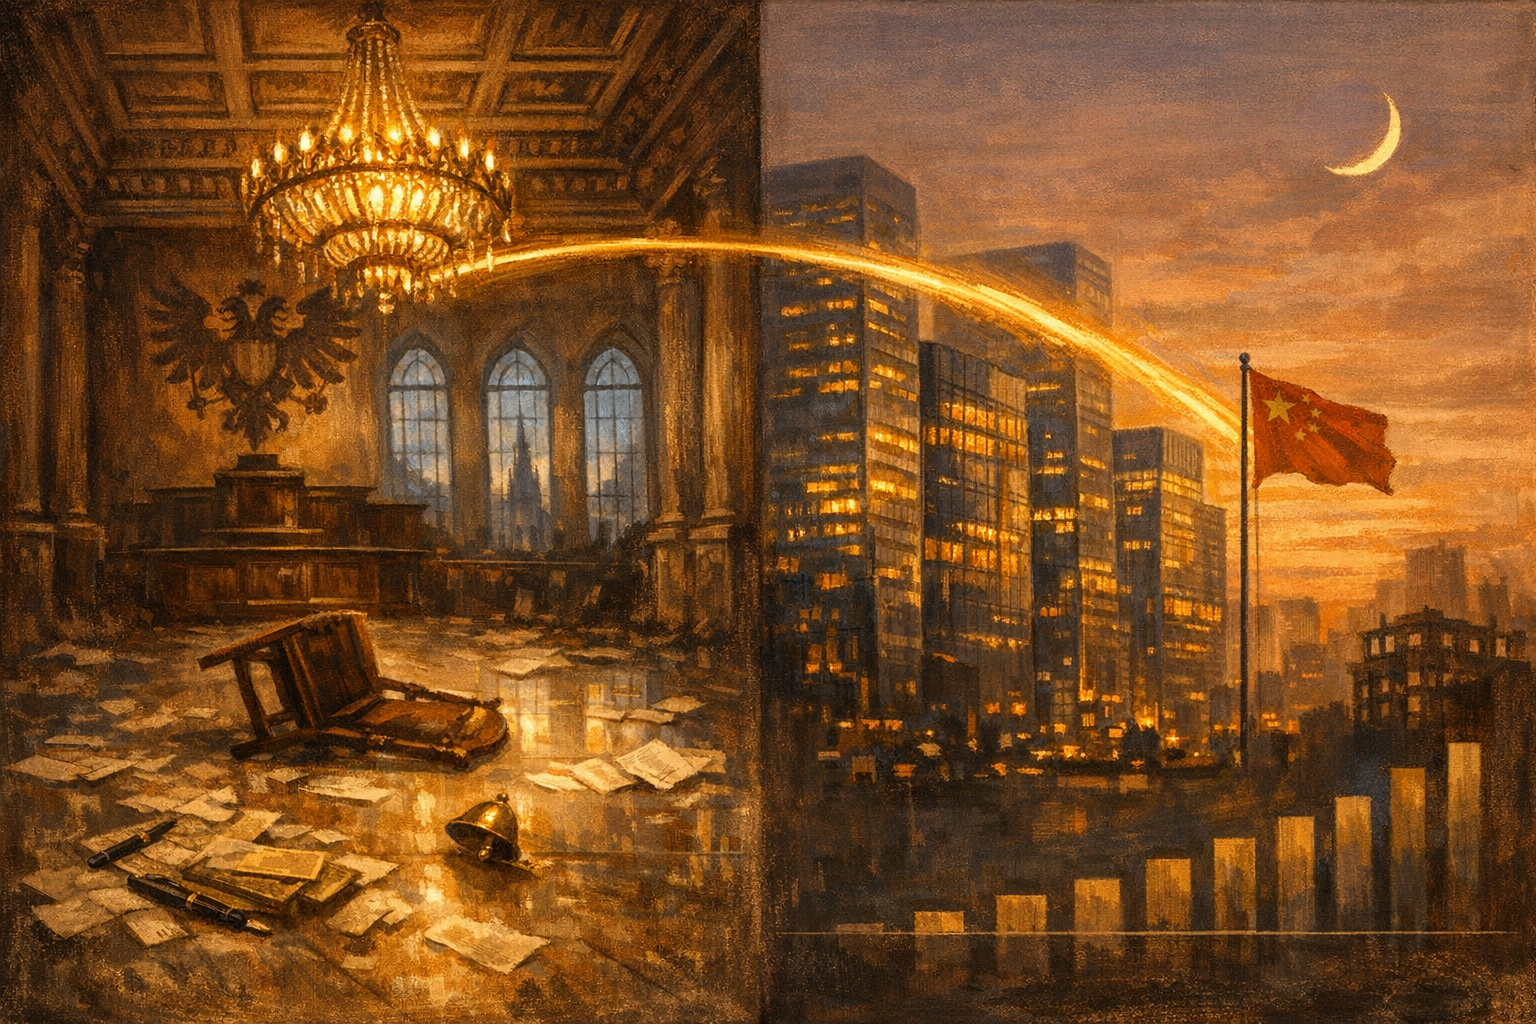
On the morning of Friday 9 May 1873, the Vienna Stock Exchange opened on what should have been an ordinary trading day in the middle of the longest speculative boom in central European history. Instead, by ten in the morning, the panic had begun. By noon there were no buyers. By the close of business that afternoon over a hundred banks and brokerage houses had failed. The Habsburg Imperial Treasury suspended trading. Black Friday on the Vienna Bourse, as the day became known almost immediately in the German-language press, was the moment the so-called Gründerzeit, the founders' period, ended.
Four months later, on 15 September 1873, the Berlin Stock Exchange followed. The pattern was identical. By the end of the year, around sixty percent of the new German joint-stock companies founded in the previous two years had been wound up. The Long Depression that followed lasted, in central Europe, until roughly 1879.
To understand what had just collapsed, one has to understand what had been built. And to understand what had been built, one has to understand where the money had come from. The money had come from France.
In May 1871, after seven months of war and four months of subsequent negotiation, the new German Reich and the new French Third Republic had signed the Treaty of Frankfurt. France ceded Alsace-Lorraine. France acknowledged the Hohenzollern annexation of Strasbourg. And France agreed to pay the German Reich an indemnity of five billion gold francs, the largest single transfer of wealth between two states in modern European history up to that point. The payment was approximately a quarter of French GDP. It was approximately twice the size of the entire German federal budget for the previous three years combined. The deadline for full payment was March 1875.
France paid it off in full in September 1873, eighteen months early.
This was not a feat of austerity. France floated two enormous public loans, one in 1871 and one in 1872, both of which were over-subscribed several times over by French and international investors who lined up around Parisian banks for the chance to lend the new Republic money on patriotic terms. France did not feel ruined. France had been embarrassed at Sedan and humiliated in Paris, but France was the second-largest creditor economy in the world after Britain, and French savings were enormous, and French banks were experienced.
The country with the problem turned out to be the recipient.
Germany in May 1871 was a brand-new political entity, proclaimed only four months earlier in the Hall of Mirrors at Versailles. It had no central bank. It did not yet have a single currency. Its capital markets were small, fragmented across the various member kingdoms, and unsophisticated by the standards of London or Paris. Into this immature financial system arrived, between 1871 and 1873, the equivalent of a quarter of France's GDP in gold-equivalent specie.
It was put to work immediately.
Roughly nine hundred new joint-stock companies were registered in the German states between 1871 and the end of 1873. Most of them existed to build railways, mostly to nowhere. Many of them existed to build tenement housing in suburban Berlin, mostly speculative. A surprising number existed simply to issue more shares. Vienna, on the other side of the Inn river, did the same on a smaller scale. The new Reich went onto the gold standard formally in 1873 and founded the Reichsbank in 1875 (a measure of how new the financial architecture really was). The flood of French gold turned into the Gründerzeit boom.
The Gründerkrach of May to September 1873 was what happens when a financial system that has spent two years absorbing more capital than it can productively deploy finally runs out of plausible borrowers. The new railways were not earning. The new tenements were empty. The new banks were undercapitalised. When confidence broke in Vienna on 9 May, it took less than four months for the same break to reach Berlin. The depression that followed lasted six years.
The deeper lesson the German financial system took from 1873 was not that France's indemnity had been malign. It was that absorbing very large foreign-currency inflows in compressed time produces speculative excess, financial fragility, and recurrent panics. That lesson was not properly digested. The Reichsbank's monetary architecture, established in the Gründerzeit period, never developed the institutional sophistication that the older Bank of England or Banque de France had spent two centuries acquiring. The same monetary fragility surfaced again in the panic of 1907. It surfaced again in the partial banking crisis of 1913. It surfaced finally, and catastrophically, in the hyperinflation of 1923, when the gold mark that France had effectively built fifty years earlier was wiped out at a final exchange rate of one US dollar to four point two trillion paper marks.
The Reich could not, in the end, hold the gold France had given it.
The Echo
The People's Republic of China ended December 2025 with three point three six trillion United States dollars in foreign-exchange reserves, the largest single national stockpile of foreign-currency assets in human history. By February 2026 the figure had risen to three point four three trillion. China's bilateral trade surplus with the rest of the world for 2025 was one point two trillion dollars, twenty percent higher than 2024 and the largest annual surplus any country has ever recorded. In the combined first two months of 2026, the monthly surplus reached two hundred and thirteen billion dollars, the largest monthly figure ever recorded.
The surplus has been there for fifteen years. The reserves have been accumulating since the 2001 World Trade Organization accession. The total transfer is not on the order of a quarter of one country's GDP. It is on the order of a quarter of the entire world's GDP, transferred in compressed time into the financial architecture of one country.
China has done what Germany did in 1871-1873, on a much larger scale, over a much longer period, and into a financial system that is, like the early Reichsbank's, structurally young.
The investments started predictably. Roughly between 2001 and 2020, China's surplus dollars were recycled into infrastructure (high-speed rail, the world's largest expressway network), into manufacturing capacity (steel, ships, electronics, increasingly EVs and solar), and most importantly into urban property. Local governments, restricted from running their own deficits, turned land sales and property-development financing into the primary mechanism by which the surplus was deployed. Roughly thirty percent of Chinese GDP, at the property sector's peak in 2020, came from property and property-related construction.
The Evergrande default of September 2021 was China's Vienna Bourse moment. The collapse of the property sector since then has wound up tens of millions of housing units that nobody plans to live in, taken several major property developers into restructuring or liquidation, left local-government financing vehicles holding non-performing assets at a scale the central government has not finished accounting for, and exposed the Chinese banking system to an unrealised loss the IMF estimates in the trillions.
The Chinese state, like the German state in 1875, has responded by trying to build the missing institutional architecture after the fact. Property-developer bailouts, central-government recapitalisation of stressed banks, and a quiet redirection of new surplus dollars away from property and into industrial export capacity (which is part of why Chinese EV exports doubled in 2025) are the visible parts of the response. The underlying problem, the one Germany also could not solve in time, is that a financial system absorbing two hundred billion dollars a month of new surplus has nowhere good to put it that it has not already saturated.
Germany absorbed five billion gold francs in two years and produced a six-year depression. China has absorbed approximately four trillion dollars in cumulative reserves and an additional four trillion in non-reserve foreign-currency assets over the past two decades, and has so far produced one major property-sector collapse, an unresolved local-government debt crisis, and a banking system whose true balance sheet remains opaque.
The Reich could not, in the end, hold the gold France had given it.
What China is going to do with its three point four trillion is not yet visible. What is visible is that it has been struggling, since 2021, to do anything useful with the marginal new dollar.
Last time, the financial fragility of the receiving country took fifty years to surface fully. It surfaced as hyperinflation.
This time, what comes next?